At least $100bn of investment for 134 new lithium mines is needed for 2050 demand
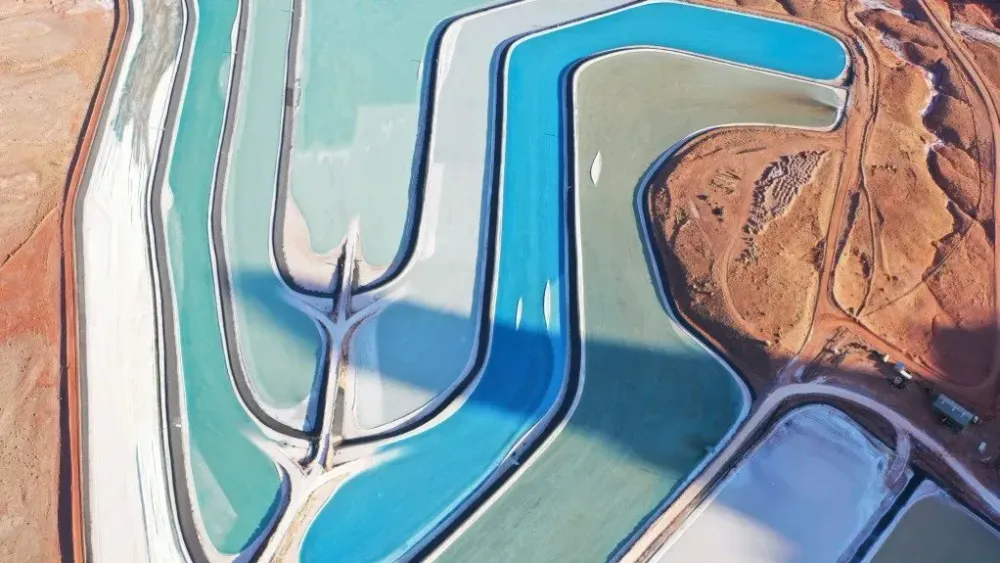
To meet 2050 lithium demand, the equivalent of 134 new lithium mines will be needed, says supply chain researcher Benchmark Mineral Intelligence.
This equates to a new mine every two months for the next 24 years, explains Benchmark Mineral Intelligence lithium product director Dr Cameron Perks.
He adds that demand growth between 2040 and 2050 alone will require 44 new lithium mines each producing about 36000 t/y of lithium carbonate-equivalent (LCE).
Benchmark Mineral Intelligence forecasts that global lithium demand will reach about seven-million tonnes of LCE in 2050, with 76% of this driven by electric vehicles (EVs).
This is an increase of 4.8-million tonnes from demand of 2.11-million tonnes of LCE in 2026.
“Meeting 2050 demand will require more than $100-billion of investment before any contribution from recycling, rising to more than 180 mines in our upside scenario,” says Perks.
“The biggest challenge is sustaining that investment through price cycles, while competing for capital with AI, defence and the wider energy transition.”
DEMAND DRIVERS
Between 2026 and 2050, lithium demand is forecast to more than triple, with the vast majority of this growth driven by the battery market.
Batteries account for 92% of lithium demand in 2026, up from around 70% in 2020.
EVs currently account for 55% of lithium demand, and this is forecast to grow to 76% by 2050 as the rapid recent growth in stationary storage moderates.
“Lithium demand from stationary storage has grown more than 60% a year for the past two years, but we expect that pace to slow significantly, to around 5% a year to the end of the decade,” Perks points out.
SOURCES
Australia is expected to be the largest producer of mined lithium in 2026, accounting for 29% of mined supply. However, Australia’s share of forecast mine supply is set to fall to 20% by 2050, even with large-scale brownfield expansions such as PLS’s P2000 factored in for a start around 2030.
“Many of Australia’s mines will be depleting by 2050. Price volatility has made financiers hesitant, and the regulatory burden is growing. It’s not too late, but if Australia doesn’t back growth, other regions will take that share," Perks emphasises.
In contrast, China’s share is set to remain relatively stable at around 25%, supported by continued investment in domestic resources and an emphasis on battery supply chain dominance.
North American supply is set to increase from 1.7% of mined supply in 2026 to 13% by 2050, as the region works to meet its own domestic requirements and reduce reliance on China. North America currently accounts for 6% of lithium demand from cell production, which is forecast to increase to 12% by 2050.
Europe is similarly targeting domestic and allied supply chain development. The region currently accounts for less than 1% of mined supply, despite accounting for 7% of lithium demand from cell production.
By 2050, 5.5% of mined lithium is forecast to come from Europe, which will take 8% of demand.
“Europe and North America face their own unique challenges. Many of the largest and most promising projects require novel technology or face environmental and community concerns. These aren’t insurmountable, but they create significant delays, and they mean mines built in these regions simply cost more," Perks states.
HIGHER CASE
This analysis assumes Benchmark’s base case. The number of mines could be significantly higher if Benchmark Mineral Intelligence's upside scenario of almost nine-million tonnes LCE of demand is realised, which would be largely driven by EV and energy storage policies worldwide.
Perks explains that in the firm's upside case, the equivalent number of mines rises to around 180, which would require well over $150-billion of new investment.
Recycling is the biggest factor that could reduce the number of new mines needed.
Benchmark Mineral Intelligence forecasts recycling will account for almost half of lithium supply by 2050.
According to the firm’s capital expenditure analysis, which assumes recycling meets a significant share of future lithium demand, the investment needed to meet 2040 lithium demand comes in at around $64-billion.
“Recycling will grow, but our base case asks a lot of it. It’s limited by how quickly batteries reach end of life, and it still needs to compete with mines on cost. Every tonne that recycling doesn’t deliver has to come from a mine," Perks concludes.