Silver market deficit expected to widen again this year
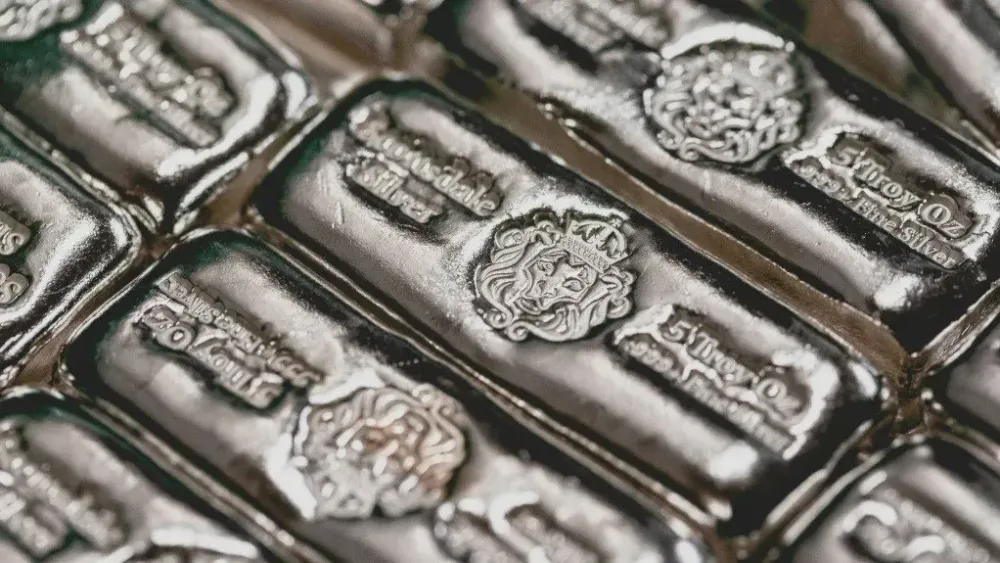
The silver market is on track to record a sixth consecutive annual deficit this year, according to the World Silver Survey published by The Silver Institute and Metals Focus.
The organisations forecast a shortfall of 46.3-million ounces this year, up from 40.3-million ounces in 2025, with global mine production expected to be flat.
Silver traded at about $60/oz on October 7, down from about $66 a month earlier.
With mines unable to grow output fast enough to close the gap, the companies drilling new high-grade silver ground, and the producers bringing new ounces online, are where investors are looking.
The Silver Institute expects total supply to slip about 2% in 2026 as mine production holds flat, so the pressure point is the same one facing most critical metals: new ounces take years to discover, define and build, and the pipeline of high-grade projects is thin.
This puts a premium on silver/lead/zinc districts in North America with historical drilling that modern exploration can now retest.
According to The Silver Institute, exploration companies are increasingly revisiting carbonate-hosted systems.
Canadian miner GoldHaven Resources, for one, has mobilised a drill rig to the D Zone target on its district-scale Magno project, in British Columbia, where drilling is targeting high-grade silver/lead/zinc mineralisation.
Notable North American silver producers and developers as of the third quarter of the year include NYSE-listed companies First Majestic Silver, which produced 3.4-million ounces of silver; Endeavour Silver Corporation, which produced 2.09-million ounces of silver; Hecla Mining, which produced 4.2-million ounces of silver in the second quarter; and Americas Gold and Silver Corporation, which recently announced a discovery grading 1062 g/t silver in Idaho's Silver Valley region.